Gallagher Bassett’s 2026 Carrier Perspective report finds social inflation, medical costs, catastrophe losses and AI-driven fraud are compounding severity and workforce pressure for carriers.
Gallagher Re’s Adam Schwebach says mid-year renewals could bring added capacity, rate reductions, and renewed appetite for underwriting hurricane risk in Florida.
Utilities across the West are increasingly cutting power during high-risk weather, reshaping wildfire prevention strategies and claims exposure for insurers.
A Bloomberg editorial urges policymakers to focus on resilience, legal reform, and mitigation rather than capping rates or penalizing insurers as premiums climb nationwide.
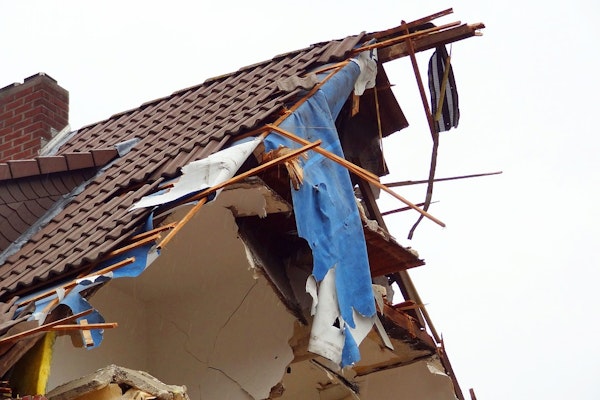
Freeze-related property damage and power outages across 14 states are driving insured losses that could make Fern one of the costliest winter storms on record.
Fitch expects broader P/C softening in 2026, while Morningstar says casualty pricing will stay out of step due to litigation and severity. Early earnings-call commentary shows carriers leaning on portfolio mix, disciplined underwriting, and AI tools to protect margins.
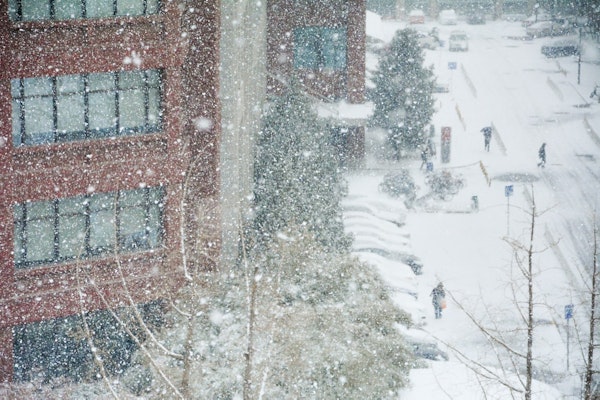
A prolonged Arctic outbreak brings snow, crashes, power outages, and freeze losses across the Southeast, raising claim concerns from auto accidents to Florida citrus damage.
Business groups argue California’s climate reporting mandates compel political speech and impose nationwide compliance burdens as the Ninth Circuit weighs constitutional limits.
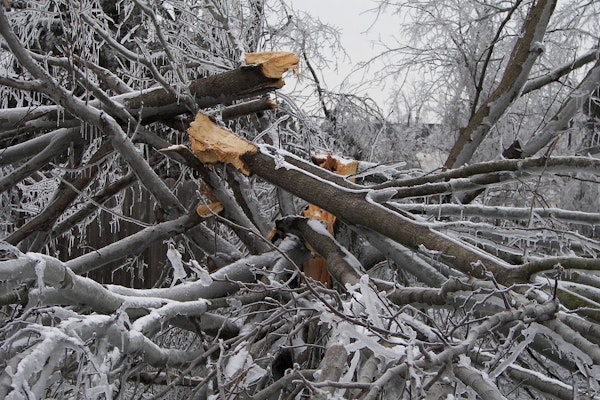
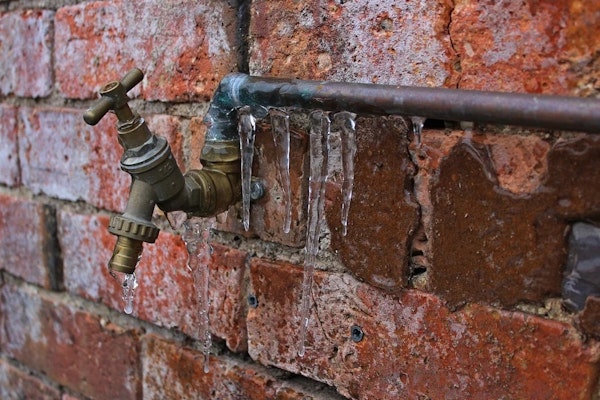
Frozen pipes, downed trees, and power outages are expected to drive additional property and auto claims as extreme cold persists across the Central and Eastern US.
New claims data shows freeze-related water losses remain a major severity driver, with average payments exceeding $30,000 and repairs stretching for months.
New research shows business interruption and system-wide losses from blackouts can dwarf insured property damage, raising questions for catastrophe modeling and resilience investment.
As data center construction surges across the U.S., insurers and adjusters confront unprecedented aggregation of values, supply chain delays, and power-related risks that complicate coverage and claims handling.
More frequent disasters are straining commercial insurance programs, forcing companies to retain more risk and explore captives to address losses that traditional policies no longer cover.
Prolonged ice, power outages, and lingering cold raise concerns over property damage, frozen pipes, and business interruption claims across much of the US.