The Institutes Knowledge Group’s 2026 Skills Report finds AI literacy, claims expertise, leadership, and risk management skills are becoming critical as insurance roles evolve.
A new Marsh report shows global transactional risk insurance claims rose 34% in 2025, with financial statement breaches accounting for more than half of total paid losses and insurers paying nearly $650 million worldwide.
Economic pressure and rising insurance premiums are driving record shopping activity, forcing carriers to rethink retention strategies, customer communication, and AI-driven workflows.
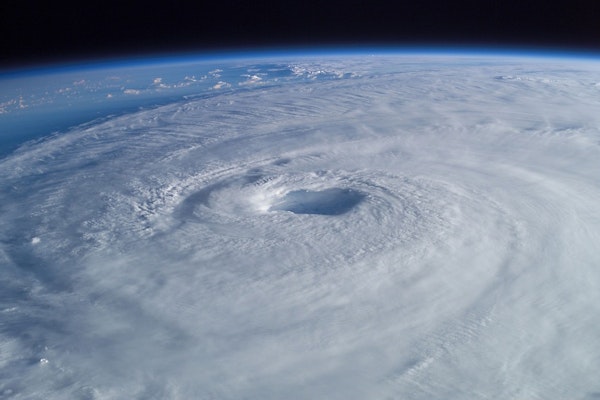
Munich Re says El Niño conditions could suppress Atlantic hurricane activity while increasing typhoon risks across the western Pacific. The reinsurer warns that even a quiet season can still produce catastrophic insured losses.
AI-powered claims handling, rising veterinary costs, and employer-sponsored coverage are reshaping the pet insurance market worldwide. Insurers are betting on faster claims payments and digital distribution to close the large uninsured pet gap in the U.S.
The U.S. property and casualty market recorded its strongest underwriting result in more than a decade in 2025, but adjusters still face elevated catastrophe exposure, litigation pressure and rising replacement costs.
Small landscaping changes can redirect water toward foundations, increase basement flooding risk, and complicate homeowners insurance claims after heavy rain or storms.
Forecasters say exceptionally warm Pacific waters and a developing El Niño could push tropical systems farther north in 2026, increasing flood and storm concerns for Hawaii and Southern California homeowners.
Severe convective storms are generating record insured losses across the United States, forcing carriers to rethink underwriting, catastrophe modeling, and homeowner pricing strategies.
Direct written premiums rose nearly 11% in 2025 as policies in force surged, but Fitch says deteriorating losses, softer pricing, and AI-driven threats are making cyber underwriting more difficult. Coverage wording and third-party risk could become bigger issues for insurers and claims teams.
New carrier-backed study shows significant drops in water damage claim frequency and severity, with implications for underwriting and loss prevention strategies.
Declining auto claims and reserve releases point to softer pricing in 2026, while liability lines continue to face reserve pressure and social inflation challenges.